Prestige Parklane EMI Calculator
Featured Image of Prestige Parklane EMI Calculator


A Prestige Parklane EMI starts around ₹37,500 a month for the ₹56 lakh 1 BHK, assuming an 80 per cent loan at 8 per cent over 20 years. Every configuration in the project maps the same way, from the 2 BHK Optima to the 3 BHK Ultima. This guide works the numbers for each home, shows the EMI per lakh at different rates, and explains what sits outside the EMI.
How the EMI Is Calculated


Every calculator runs the same formula: the loan amount, the monthly interest rate and the tenure in months decide a fixed instalment. Three levers move your number, and only three.
  • The loan amount: the price minus your own contribution, capped by the bank's loan-to-value rules.
  • The interest rate: large lenders start around 7.25 to 7.75 per cent in late 2026, varying with your credit profile.
  • The tenure: longer tenures cut the monthly EMI but raise the total interest paid.

EMI Per Lakh: The Quick Reckoner


Multiply the figure below by your loan in lakhs and you have your EMI without any tool at all.

Rate 15 years 20 years 25 years
7.5 per cent ₹927 ₹806 ₹739
8 per cent ₹956 ₹836 ₹772
8.5 per cent ₹985 ₹868 ₹805
9 per cent ₹1,014 ₹900 ₹839

EMIs for Every Parklane Configuration


The table assumes the maximum bank funding each price allows, 80 per cent up to ₹75 lakh and 75 per cent above it, at 8 per cent over 20 years. Your sanction and rate will set the exact figure.

Home Launch price from Loan assumed Indicative EMI
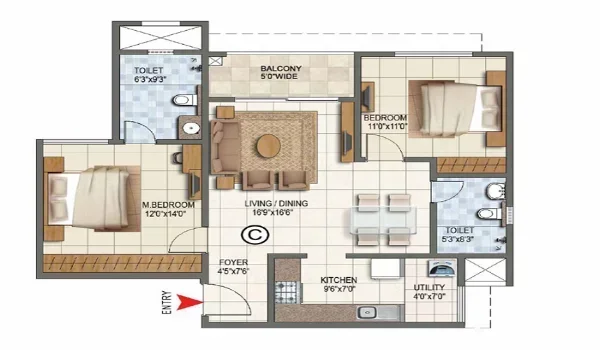
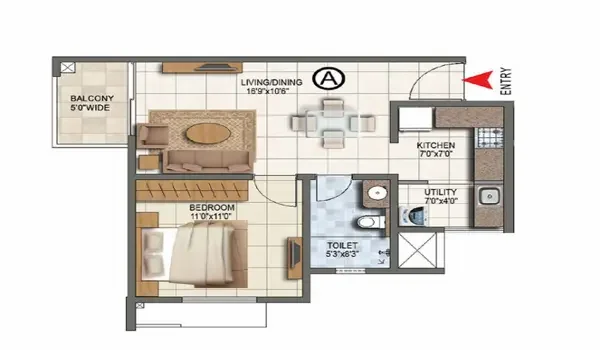
1 BHK Classic, 567 sq ft ₹56 lakh ₹44.8 lakh About ₹37,500
2 BHK Optima, 828 sq ft ₹82 lakh ₹65.6 lakh About ₹54,800
2 BHK Ultima, 1,087 sq ft ₹1.02 crore ₹76.5 lakh About ₹64,000
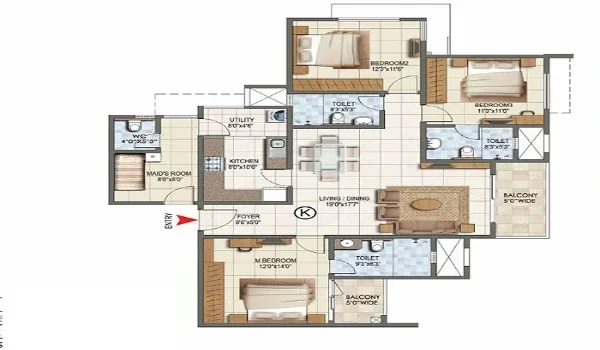
3 BHK Aspire, 1,445 sq ft ₹1.32 crore ₹99 lakh About ₹82,800
3 BHK Premia, 1,597 sq ft ₹1.46 crore ₹1.1 crore About ₹91,500
3 BHK Ultima, 1,757 sq ft ₹1.64 crore ₹1.23 crore About ₹1,02,800

What the EMI Does Not Cover


Budget the costs that stay outside the loan, because they arrive from your own funds. GST runs at 5 per cent on every payment, stamp duty and registration at 7.65 per cent, and other charges of saleable area × ₹415 plus ₹25,000 fall due at possession.

On the ₹56 lakh 1 BHK those extras take the all-in cost to about ₹65.9 lakh, against a bank loan of ₹44.8 lakh. The gap is what your savings must bridge across the four-year payment plan.

The EMI Builds Up in Stages


Because the payment plan is time-linked, the bank releases money gradually: 20 per cent across booking and agreement, then 3.2 per cent every two months from December 2026 to October 2030. Your interest cost grows with each release rather than starting at the full figure.

During construction you can pay pre-EMI, interest only on the amount drawn, or start the full EMI early and begin cutting principal. The full instalments in the tables apply once the loan is completely drawn, around possession on 31 December 2030.

Ways to Bring the EMI Down


  • Stretch the tenure: the ₹44.8 lakh loan falls from about ₹42,800 over 15 years to about ₹34,600 over 25.
  • Improve the rate: a 750-plus credit score and a comparison across three lenders routinely saves a quarter per cent.
  • Raise your contribution: every extra lakh you put in cuts the EMI by roughly ₹836 at 8 per cent over 20 years.
  • Prepay early: floating-rate home loans carry no prepayment penalty, and early principal cuts save the most interest.

FAQs


1. What is the EMI for a 1 BHK at Prestige Parklane?

About ₹37,500 a month on a ₹44.8 lakh loan at 8 per cent over 20 years, assuming the ₹56 lakh launch price and 80 per cent funding.

2. What is the EMI for a 3 BHK?

From about ₹82,800 for the Aspire at ₹1.32 crore, rising to about ₹1,02,800 for the Ultima at ₹1.64 crore, on 75 per cent loans at 8 per cent over 20 years.

3. How do I estimate an EMI quickly?

Multiply your loan in lakhs by the per-lakh figure: ₹836 at 8 per cent over 20 years, or ₹806 at 7.5 per cent.

4. Does the EMI start at booking?

No. Disbursement follows the time-linked plan, so interest builds in stages, and the full EMI applies once the loan is fully drawn.

5. What costs sit outside the loan?

GST at 5 per cent, stamp duty and registration at 7.65 per cent, and other charges at possession, all typically from your own funds.

6. Are these figures guaranteed?

No. They are illustrations at assumed rates and funding levels. Your bank's sanction letter and the current price sheet give the binding numbers.

Prestige Parklane Blog


Enquiry
Enquire Now