Home Loans for Pre-Launch Apartments
Featured Image of Home Loans for Pre-Launch Apartments


A home loan for a pre-launch apartment works like any other, with three extras. The project must clear the bank's own approval, the money is released in stages against the payment plan, and you may pay pre-EMI interest while the towers rise. Rates in late 2026 start around 7.25 to 7.75 per cent at the large lenders. Here is the eligibility maths and the process, step by step.
What Decides Your Eligibility


  • Income and obligations: banks typically allow total EMIs up to about half of your net monthly income, with existing loans counted in.
  • Credit score: 750 and above earns the advertised rates; lower scores pay more or face smaller sanctions.
  • Age and tenure: the loan must usually close by retirement age, so younger borrowers get longer tenures and smaller EMIs.
  • Employment record: stable salaried income or two to three years of business returns, with the paperwork to show it.
  • Co-applicant: adding a earning spouse or parent raises the eligible amount and can improve the rate.

How Much Banks Will Fund


The Reserve Bank caps the loan against the property's value, and the cap tightens as the ticket grows. Your own contribution covers the rest, plus the costs banks do not fund.

Home price Maximum loan-to-value Your minimum contribution
Up to ₹30 lakh 90 per cent 10 per cent
₹30 lakh to ₹75 lakh 80 per cent 20 per cent
Above ₹75 lakh 75 per cent 25 per cent

Plan for the unfunded costs too. GST at 5 per cent on an under-construction home, stamp duty and registration at 7.65 per cent in Karnataka and the project's other charges all generally come from your own funds.

The Pre-Launch Checks That Matter


Before any bank lends on an under-construction project, it verifies the project itself, and you should run the same checks first.

  • RERA registration: confirm the number on the state portal. Prestige Parklane, for example, is registered as PRM/KA/RERA/1251/309/PR/150926/008941, valid till 31 December 2030.
  • Bank project approval: most lenders maintain approved-project lists, and a tier-one developer's launch is usually cleared early.
  • Title and plan approvals: the RERA filing discloses the land title, the sanctioning authority and the declared completion date.
  • The payment plan: know the dates you are committing to, because your disbursements will follow them.

The Process From Booking to Disbursal


The sequence runs: sanction, agreement, then staged disbursement. Get a sanction letter early, ideally before you book, so your budget is a bank's number rather than your guess.

After booking, you sign the agreement to sell, pay stamp duty and submit the builder's demand letters to the lender. The bank then releases each instalment directly to the developer as it falls due, against the schedule in your agreement.

At Prestige Parklane the plan is time-linked: 10 per cent on booking, 10 per cent on agreement, then 24 instalments of 3.2 per cent every two months to October 2030. A lender funds those dates as they arrive, which makes your outflow unusually predictable.

Pre-EMI or Full EMI


Until the loan is fully drawn, banks offer two ways to pay. Pre-EMI means paying only the interest on what has been released, which keeps outgo low during construction but repays no principal.

Full EMI from the first disbursal costs more each month and starts cutting the principal immediately. Choose pre-EMI if you are paying rent elsewhere during construction, and full EMI if you want the loan shrinking from day one.

Documents to Keep Ready


  • PAN, Aadhaar and address proof, with photographs.
  • Three to six months of salary slips and bank statements, or business financials for the self-employed.
  • Form 16 or income tax returns for two to three years.
  • The booking form, cost sheet and builder demand letters for the chosen apartment.
  • Existing loan statements, so the bank can compute your true capacity.

Frequently Asked Questions


1. Will I get a home loan for a pre-launch apartment?

Yes, once the project is RERA-registered and clears the bank's project approval. Tier-one launches are usually approved quickly.

2. What credit score do I need?

Around 750 or higher for the best rates. Lower scores can still qualify, at a higher rate or a smaller sanction.

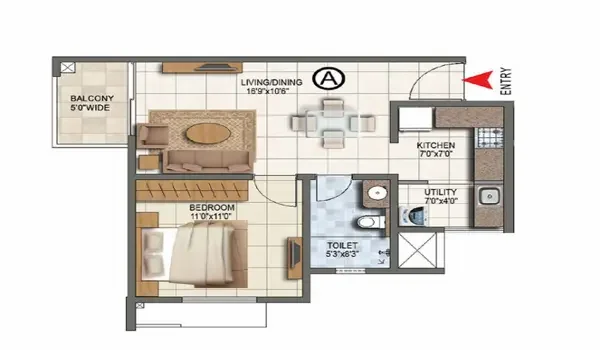
3. How much loan can I get on a ₹56 lakh 1 BHK?

Up to 80 per cent, about ₹44.8 lakh, since the price falls in the ₹30 to ₹75 lakh band. GST, stamp duty and other charges are extra, from your funds.

4. How is the loan released for an under-construction home?

In stages. The bank pays the developer against each demand letter, following the payment plan dates in your agreement.

5. What is pre-EMI?

Interest-only payments on the amount disbursed so far. Your full EMI, covering principal too, begins once the loan is fully drawn.

6. What are home loan rates now?

Large lenders start around 7.25 to 7.75 per cent in late 2026, varying with credit score, loan size and bank. Confirm current rates before you apply.

Prestige Parklane Blog


Enquiry
Enquire Now